While inflation has moderated, household budgets remain under pressure. At the same time, heightened promotional activity, intensifying competition and changing shopper expectations are reshaping not only what shoppers buy, but where they look for products, how they evaluate them and where they ultimately make a purchase.
These shifts are explored in Trade Intelligence’s latest Health and Beauty Report, which examines the changing shopper behaviours, retail dynamics and category trends shaping growth in the market.
Where shoppers buy health and beauty products
Perhaps the clearest shift is that there is no single health and beauty shopping destination. Shoppers move between specialist health and beauty retailers, supermarkets, e-commerce platforms and other channels depending on what they need.
“True retailer exclusivity is rare,” says Andrea Slabber, Insights Lead at Trade Intelligence. “Health care shoppers use an average of 2.4 different store types, while personal care shoppers use an average of 2.2, splitting visits across specialist chains, supermarkets, e-commerce and informal channels.”
Clicks and Dis-Chem remain important destinations, particularly where shoppers are looking for range, new products and advice. But supermarkets compete strongly on a different set of needs. In personal care, Clicks and Dis-Chem lead perceptions of new products and range respectively, while Shoprite leads on price.
The result is a market in which different retailers play different roles in the shopper’s repertoire. Specialist retailers bring category depth, credibility and innovation, while supermarkets combine health and beauty purchases with convenience, accessible pricing and broader household shopping missions.
While physical retail still dominates, shoppers increasingly use online resources before making an in-store purchase, meaning that online sales alone understate the role digital plays in the path to purchase.
Nearly half of personal care shoppers surveyed by Ti say they are often or very often influenced by online reviews. In health care, shoppers lean heavily on online reviews, but also on recommendations from friends and family.
Township shoppers provide another example of why assumptions about channel choice can be misleading. Among personal care shoppers living in townships, 81% shop at pharmacies or specialist health and beauty retailers and 63% at supermarkets or hypermarkets.
“The reality is that most township shoppers prefer to purchase health and personal care products through larger retail chains,” says Slabber. “Specialist health and beauty retailers are particularly important, while supermarkets also play a strong role in personal care.”
Corporate retailers are increasingly bringing those formats closer to township communities. Boxer has invested in its health, baby and personal care sections, Usave maintains a strong personal care focus, while Clicks has introduced its smaller-format KwaMakhi concept, with a curated range and an emphasis on everyday low prices and smaller affordable packs.
Informal trade nevertheless presents an interesting indirect route into these communities, particularly where specialist wholesalers are not accessible. Trade Intelligence is observing informal traders, salon owners and practitioners purchasing higher-end health and beauty products through multi-buy promotions at retailers such as Clicks and Dis-Chem, and then bringing those products into local markets. In other words, these products may reach township shoppers through informal sellers even where suppliers have not established dedicated informal channel distribution.
What health and beauty shoppers are buying
The shifts in where shoppers shop are being matched by changes in the categories themselves.
Health care, while the smallest of the three major segments, is forecast to grow fastest in 2026.
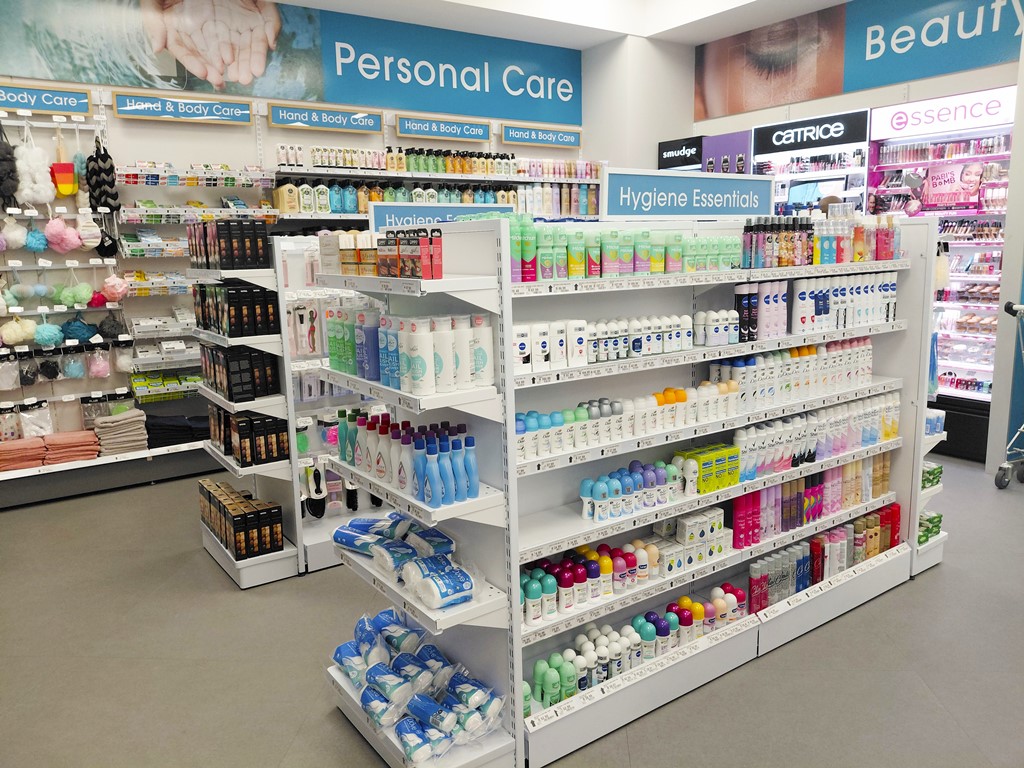
Personal care remains the largest segment, accounting for just over half of the total health and beauty market. This category is seeing a rapid expansion of newer product formats such as body scrubs, face masks, serums and body oils. This influx is intensifying competition for shelf space and, in some cases, displacing more established products such as tissue oils and glycerine.
In beauty, fragrance is now the largest sub-category, narrowly ahead of cosmetics. Mass-market fragrance represents 84% of the fragrance category.
Economic pressure does not mean consumers have abandoned discretionary categories altogether. Shoppers are seeking small, affordable luxuries. At the same time, private brands are making self-care more accessible: two-thirds of both health care and personal care shoppers surveyed say they are maintaining or increasing their private brand purchases, largely based on perceptions of value for money and quality.
Wellness is also stretching the boundaries of what health and beauty products are expected to deliver. Beauty routines are increasingly positioned as sensory self-care experiences, while mood-enhancing products, nostalgic fragrances, sensorial textures and colour cosmetics tap into the emotional as well as functional benefits of the category.
“Products, promotions and messaging need to reflect the shopper mindset in each retail environment, bearing in mind that shopper repertoires now incorporate a combination of channels, retail formats and retail brands,” says Slabber.
In a R116.8 billion market, the growth opportunity is therefore not simply about identifying which categories or channels are expanding. It is about understanding how shoppers are moving between them – and ensuring that the right product, price, pack and proposition meet them wherever they choose to shop.