New Q3 2026 Debt Index findings raise questions about household cash flow, borrowing habits and the real value of income.
South Africans may be earning more on average, but new findings on consumer debt suggest that rising income does not necessarily translate into financial security. Nkobane Consulting is calling for a more informed conversation about the relationship between personal income, debt commitments and the cost of maintaining a household.
The Q3 2026 Debt Index findings provide a stark picture of the pressure experienced by consumers seeking debt counselling. According to the Index, applicants need an average of 65% of their take-home pay to service debt, while their overall debt-to-annual-net-income ratio stands at 126%. The figures highlight how debt repayments can absorb a substantial share of income before households have paid for essentials such as food, transport, electricity and housing.
The pressure is not confined to lower-income consumers. Applicants taking home more than R50,000 per month are using 97% of their take-home pay to service debt and have a debt-to-income ratio of 300%. This challenges the assumption that a higher salary automatically creates financial resilience. Income matters, but so do the level of existing commitments, borrowing decisions and the amount left available after repayments.
Multiple credit commitments are adding to the squeeze
The Index reports that new applicants have an average of 8.8 credit agreements, with 96% holding a personal loan. It also records an increase in the proportion of new applicants with a one-month payday loan, from 57% to 64% year-on-year. Banks account for 65% of new applicants’ debt, while non-bank lenders account for 15%, the highest share since the Index began.
For households, these figures raise important questions about cash-flow management and the cumulative cost of servicing several credit agreements. Where short-term borrowing becomes a way to bridge recurring gaps between income and expenses, consumers can find themselves with less room to absorb unexpected costs or build savings.
The cost of living puts disposable income under pressure
The Index records average net income among incoming applicants increasing by 31% since 2021, compared with CPI growth of 27%. However, income growth has not been even across income bands. Over the period referenced in the report, petrol prices increased by 46% and electricity tariffs by 101%.
The pressure is particularly visible in grocery spending. Groceries account for 50% of disposable income for applicants earning below R10,000 per month, and 38% for those earning between R10,000 and R20,000. These figures illustrate how quickly essential expenses can reduce the money available for debt repayments, savings and other household needs.
A timely conversation ahead of Black Friday and the festive season
With Black Friday and the festive season approaching, consumers are being encouraged to consider the longer-term implications of taking on additional credit to fund seasonal spending. A purchase that appears affordable in the moment can place further pressure on future monthly budgets when repayments are added to existing commitments.
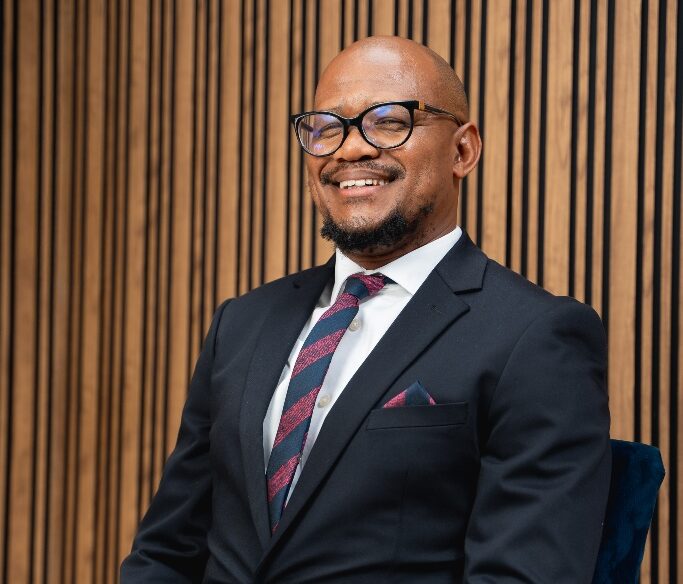
Nkobane Consulting CEO Maphetla Motsepe is available to unpack the findings and discuss the wider financial implications for South African households. The conversation can explore how consumers assess affordability, understand their financial commitments, manage cash flow and make more informed decisions about borrowing and spending.
The Index also points to the possibility of recovery: debt counselling graduates are approximately 15 times the 2016 level, and graduates in Q3 2026 paid approximately R613 million to creditors while under debt counselling. This provides an opportunity to discuss the value of structured support and informed financial decision-making, without stigmatising people experiencing financial difficulty.
As South Africans prepare for the final spending period of the year, the central question is not simply how much people earn, but how much of that income remains after debt repayments and essential expenses. Understanding that gap is an important step towards more sustainable household financial decisions.
[Statistics in this release are drawn from the Q3 2026 Debt Index findings supplied in the November 2026 media relations strategy. The figures relate to consumers applying for debt counselling and should not be interpreted as representing all South African consumers.]